Trades we insure
Every trade is priced a little differently, because every trade has different claims. These are the contractors we quote most often. If yours isn't here, call anyway. We probably write it.
- Handyman
- Small jobs, lots of them, often in people's homes. Liability is the core policy. Carriers ask what work you do and don't do, so a clear list of your services gets a better price than a vague one.
- Roofing
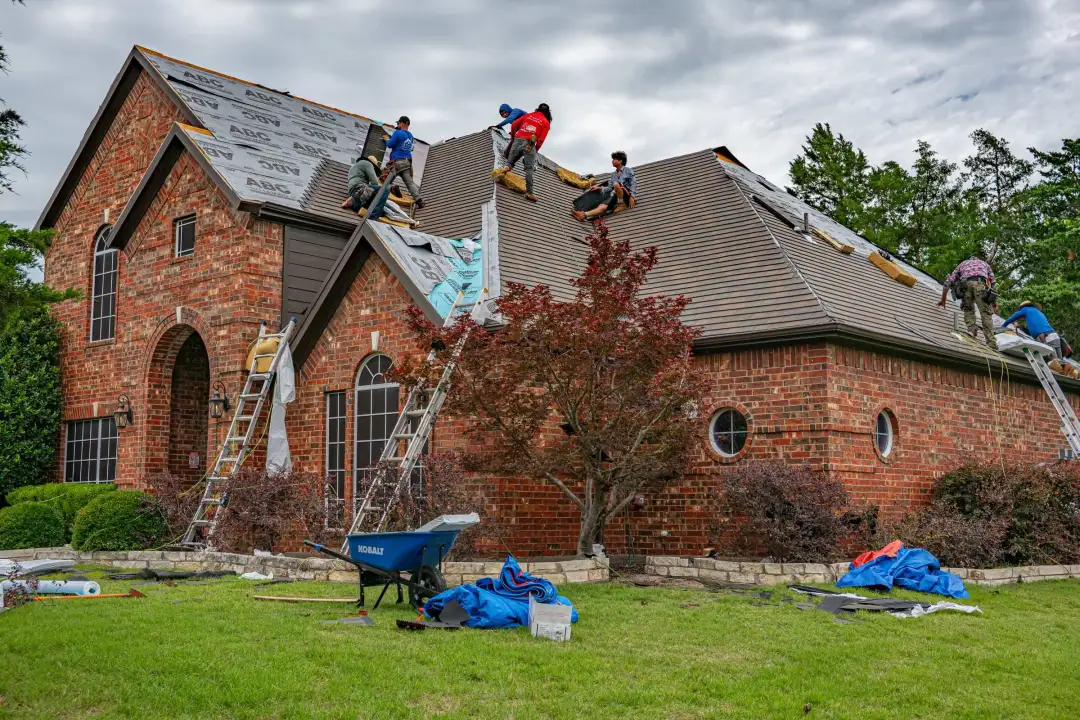
- Roofers pay more than most trades because falls and water damage lead to bigger claims. Carriers look at residential vs. commercial work, steep-slope work and how many years you've been in business. We shop roofing with several carriers because the price spread is wide.
- Plumbing
- The biggest plumbing claims are water damage after the job is done. Completed-operations coverage inside your general liability is what pays for those, so we check that it's there and at the limit your contracts ask for.
- HVAC
- Texas requires licensed air conditioning and refrigeration contractors to carry general liability. TDLR sets the minimum at $100,000 per occurrence for a Class B license and $300,000 per occurrence for Class A, with matching completed-operations and aggregate limits. Most GCs ask for more, so we usually quote $1,000,000.
- Electrical
- TDLR requires licensed electrical contractors to carry general liability of at least $300,000 per occurrence, $600,000 aggregate and $300,000 for products and completed operations. The same license application asks for proof of workers' comp or a notice that you've chosen not to carry it.
- Landscaping and lawn care
- Landscapers need liability for thrown rocks and damaged irrigation, auto for the truck and trailer, and tools coverage for mowers and equipment. Our landscaping insurance guide goes through each one.
- General contractors
- GCs carry their own liability and also collect certificates from every sub. We help with both sides: your own policy, and checking that your subs' certificates name you the way your contract says.
- Painters and remodelers
- Interior work in occupied homes means property damage is the main risk. Carriers price painters and remodelers on payroll or revenue, and on how much of the work is done by subs.