Umbrella and Boat Insurance in Texas
Somra Insurance Agency also writes umbrella and boat insurance, so one agent can look at the whole picture. Call 281‑766‑0619 for a quote on either, or pick a section below.
Umbrella insurance
An umbrella policy adds liability coverage on top of your home and auto policies. The Texas Department of Insurance describes it this way: umbrella policies can protect your assets by paying large medical and repair bills that a court or your insurance company says you're responsible for paying. TDI says coverage usually starts around $300,000 and pays up to at least $1 million.
It kicks in when a claim runs past the liability limit on your home or car policy. Think of a serious car accident you cause, a dog bite, or a guest who falls at your house. TDI notes an umbrella can also cover claims your home or auto policy may not, like false arrest, defamation and slander.
Texas law doesn't require an umbrella policy. People buy one because a judgment can reach savings, a home or future wages once the underlying limits run out. Carriers usually ask you to carry certain liability limits on your home and auto first, and we set those up to fit.
Who tends to look at one? Homeowners with equity to protect, families with teen drivers, people with a pool, a boat or rental property, and business owners whose name is on a lot of paperwork. If a lawsuit could reach more than your current limits, it's worth a five-minute call to price it.
Price depends on the number of homes and cars you insure, how many drivers are in the house (teens count most), a pool or trampoline, any boats, and the limit you choose. Because it sits on top of your other policies, an umbrella is usually one of the cheaper ways to buy a lot more protection. Call us and we'll price $1 million and $2 million side by side.
Boat insurance
Boat insurance covers damage to your boat, motor and trailer, theft, and your liability if someone gets hurt or another boat is damaged. It can also cover towing on the water, fuel spill cleanup, and your gear. Most lenders require it on a financed boat, and many marinas and storage lots ask to see proof.
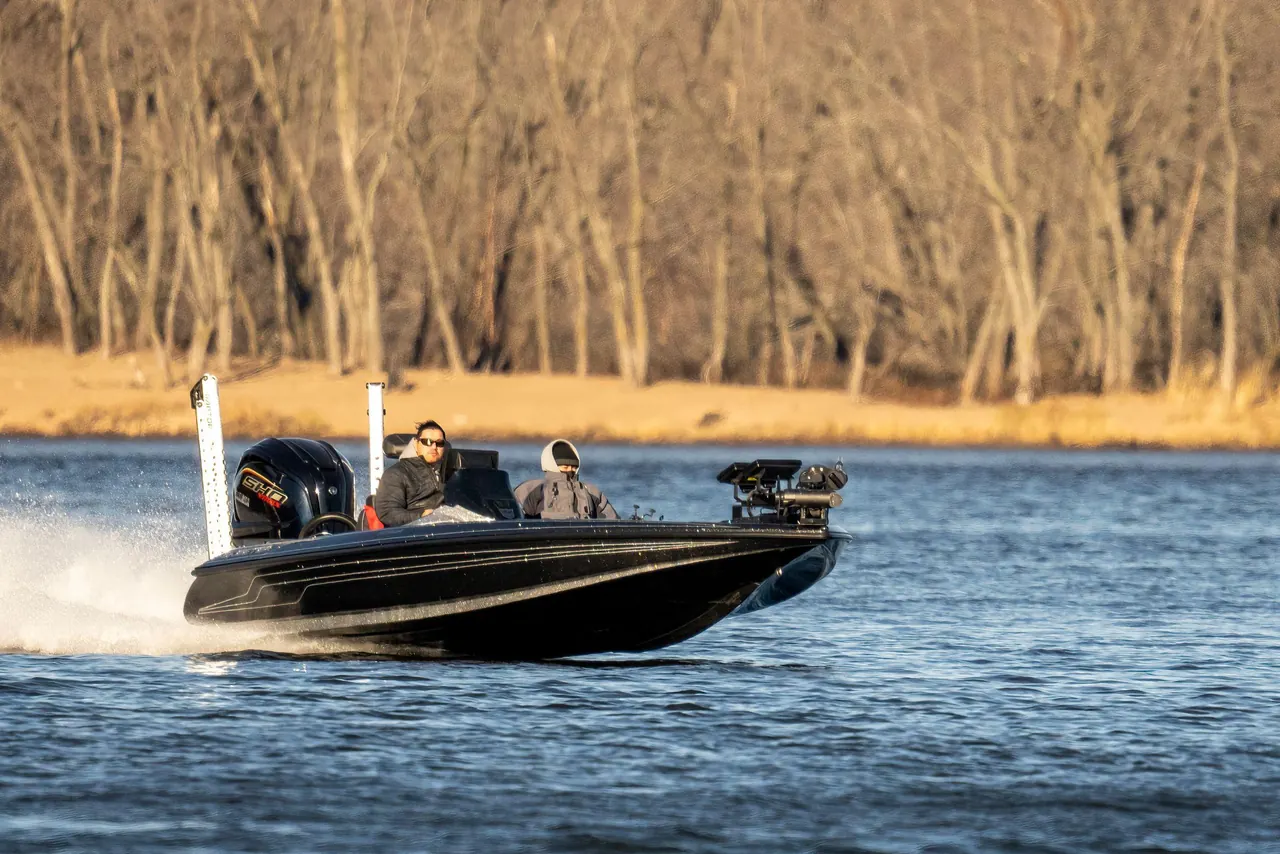
What moves the price: the boat's value, type and horsepower, where you keep it and how you trailer it, your boating experience, and the lakes or waters you run. A bass boat on Lake Lewisville prices differently from an offshore boat in Galveston. We quote agreed value and actual cash value so you can see the tradeoff.
Texas boaters also ask about the trailer. The trailer is covered for physical damage on many boat policies, but liability while you tow it usually comes from your auto policy. We check both so a wreck on the way to the lake doesn't fall between two policies. If you store the boat at home, we also look at how your homeowners policy treats it, because many home policies cap coverage for boats and motors at a low amount.
For the details on hull, liability, uninsured boater and personal watercraft coverage, read our personal boat insurance guide.
Umbrella and boat questions
Service is our only policy
Phone call or email. We know you're busy, so reach out to us however it best fits into your life. Call 281‑766‑0619.